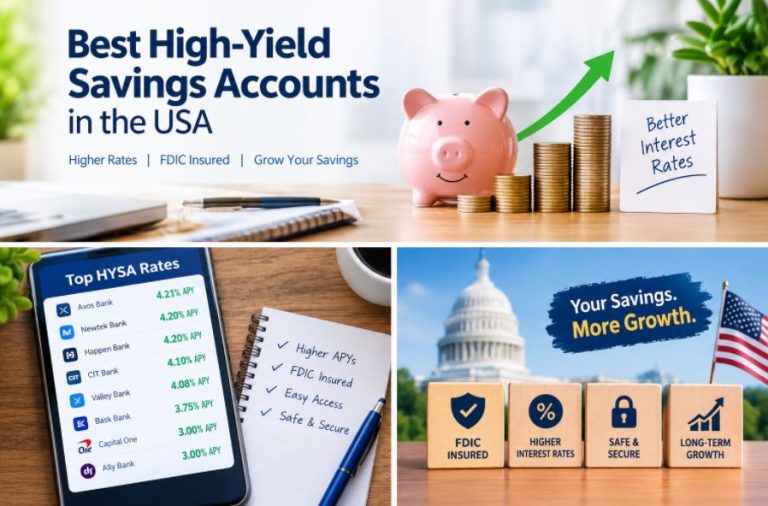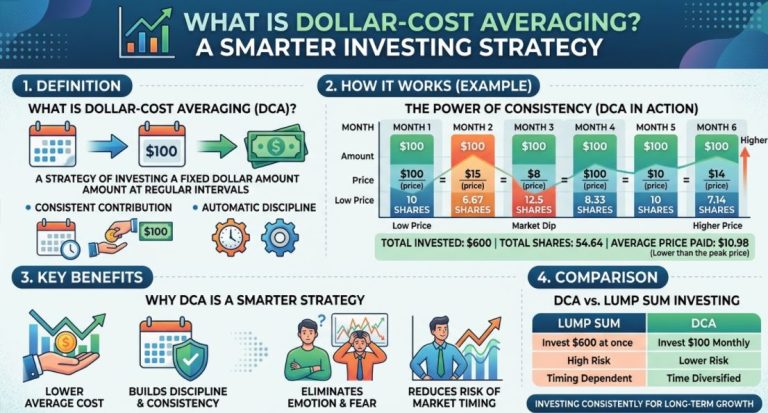
Investing vs saving are two important steps toward financial stability and long-term wealth. Whether you want to buy a home, prepare for emergencies, cover education costs, or enjoy a comfortable retirement, managing your money well can help you reach your financial goals.
Even though saving and investing are connected, they have roles. Saving is good for keeping money safe for things you need soon, while investing gives you a chance to increase your money over the years. Learning how each one works can make it easier for you to choose financial options.
What Is Saving?
Saving means putting some of the money you earn aside. You do this to use it later for things you need or for surprises. It works well for goals that happen soon. This is because you can get the money easily. Having money saved can help you pay for problems without having to sell things you own.
Benefits of Saving Money
- I create a budget and keep track of my budget.
- I set a savings goal for each month and stick to that savings goal.
- I save a portion of my income soon as I receive my income.
- I reduce subscriptions and reduce impulse purchases.
- I build an emergency fund that covers months of essential expenses and I build that emergency fund.
Disadvantages of Saving
- Money in savings accounts doesn’t earn much interest.
- Over time, inflation means your money can buy less.
- If you only save, your money might not grow enough for your long-term goals.
- Also, if it’s too easy to get your money, you might end up spending it when you don’t need to.
What Is Saving?
Benefits of Investing
- Long-term growth: Investments may help your money grow over years. I think this is an approach.
- Compounding: Earnings can create earnings when you reinvest returns. I see that this builds wealth.
- Income opportunities: Some investments can give you dividends, interest or rental income. I believe this can provide cash.
- Financial goals: Investments can help you prepare for retirement or other long-term objectives. I think this supports your plans.
Disadvantages of Investing
- Investment prices can go up and down a lot.
- You might lose part of your money. Lose all of it.
- Some investments are hard to sell or cost a lot to sell.
- Fees and taxes can take away, from your profits.
Popular Investment Options
- Stocks: When you buy stocks you are purchasing a part of a company. These can grow in value over time. Their prices can also change a lot from day to day.
- Bonds: With bonds you are lending money to a government or business. In return you get interest payments. The safety of your money depends on the creditworthiness of the borrower.
- Mutual Etfs: These investment options let you own a piece of different assets at once which helps reduce risk.. Each fund has its own fees and potential risks.
- Real Estate: Owning property can bring in income or increase in value over time. However it often costs a lot upfront. Involves ongoing costs, like maintenance and taxes.
How to Balance Saving and Investing
1. Create a Monthly Budget
Begin by listing your income, necessary expenses, debt payments and optional spending. A budget shows how money you can truly save or invest.
2. Build an Emergency Fund
Put money for unexpected expenses before putting large sums into investments that can swing in value. Start with a doable goal and add more over time.
3. Manage High-Interest Debt
High-interest debt can slow progress. Compare the cost of debt with the returns of investing and think about paying expensive debt first while keeping essential emergency savings.
4. Set Separate Financial Goals
Split goals into short‑term, medium‑term and long‑term groups.
For instance savings may fit year’s tuition or a home repair. Investments may suit retirement or another far‑off goal, based on how risk you can handle.
5. Invest Consistently
Pick a modest amount to save each time. After all essential needs are met think about making investments that fit the budget.
Adjust the amounts if income changes. Consistency is usually better than guessing the time to invest.
6. Review Your Progress
Check finances from time to time to see if savings are enough and if investments still fit the goals. Take into account changes, in income, expenses, time horizon, fees and risk tolerance.
Saving vs. Investing: Which Is Better?
You should generally save money if you need it soon, want to be ready for emergencies, or can’t afford to lose the money you’re setting aside.
Investing might be a better choice if you have more time before you need the money, your immediate financial needs are covered, and you can handle the value going up and down.
For instance, you probably shouldn’t risk money you need for rent next month in the stock market. But, money you’re saving for retirement decades from now could potentially grow more if you invest it wisely.
Understanding Compound Growth
I think compounding happens when the moneyyou earn from an investment keeps earning money over time. If you put your earnings back into the investment compounding can grow more but real results will depend on how the investment performs.
For instance imagine you put $1,000 into an account. It makes a 5% return each year. After one year the account would be $1,050 before any fees or taxes. If the same 5% return happened again year and you left the earnings in the account the account would be $1,102.50.
This example is, for illustration; it is not a prediction. In life investments do not give the same return every year and you can lose money.
Starting early and putting money in regularly gives your money time to grow.. It is important to pick investments that fit your needs and how much risk you can handle.
Common Saving and Investing Mistakes to Avoid
Avoiding mistakes can help you manage money more effectively. FDIC Stay aware of overspending. Keep track of your expenses. Avoid using credit cards for purchases. Plan your budget carefully. Save regularly even if it’s a small amount. Avoid buying. Stick to your goals. Pay bills on time to avoid fees. Build an emergency fund. Avoid taking on much debt. Focus on long-term financial health. Small choices make a difference, over time.
- Not saving any money after you earn it.
- Putting your emergency money into investments that change a lot in value.
- Thinking you will always make money from your investments.
- Putting all your money into one place.
- Taking loans to invest without knowing the dangers. Deciding to invest based on feelings when the market goes up or down.
Why Starting Early Matters
Starting early gives your investments time to benefit from compounding. Compounding happens when investment earnings are put back into the investment and start earning money on their own.
For example if you invest regularly over years your portfolio can grow because of both your contributions and the returns, on your investments. Actual results will depend on how the market performs, the fees you pay taxes and other factors.
Starting with an amount you can afford and increasing it as your income grows can be a practical and realistic approach.
Common Mistakes to Avoid
- Not having a budget: Without knowing your budget it can be hard to save money all the time.
- Investing emergency money: When the market falls you may have to sell investments at a price.
- Keeping all long‑term savings in cash: If your returns are lower than inflation your cash buys less over time.
- Chasing profits: When an investment promises very high or guaranteed returns you should look at it closely.
- Ignoring diversification: Putting much money into one thing can raise risk.
- Making decisions: Selling in a panic or buying on a whim can break your long‑term plan.
- Forgetting fees and taxes: These costs can take away, from the money you keep.
- Avoiding these mistakes can help you build a more sustainable financial strategy.
Conclusion
Investing and saving are parts of a healthy financial plan. Saving gives protection and helps you prepare for short‑term needs. Investing gives opportunities to build long‑term wealth with a level of risk.
I believe that by creating a budget building an emergency fund, managing debt and investing according to your goals you can take steps, toward financial independence.